- Chennai
- Tamil Nadu
- India
- World
- EntertainmentEntertainment
- Business
- Sports
- Lifestyle
- Technology
- Videos
- Explainers
- Editor's Picks
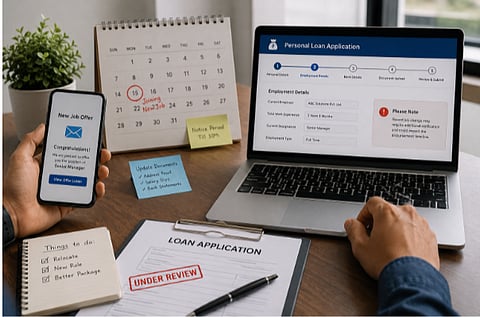
CHENNAI: Changing jobs is exciting until a pending loan makes the transition feel uncertain.
You may have already submitted your details, planned your expenses, and then accepted a better opportunity, only to wonder whether the switch could affect your personal loan disbursal.
Therefore, knowing what can delay a personal loan disbursal can help you plan better. In this blog, you will learn how a job change during personal loan application can affect processing, verification and disbursal.
Yes, a job change can cause a personal loan disbursal delay when it creates new verification or documentation requirements. However, the employment change itself does not automatically make your personal loan application unsuccessful.
Here is what can happen:
● Your employer details may no longer match the information you provided when you applied for a personal loan.
● Your new salary may differ from the income used to assess your personal loan eligibility.
● Your lender may request current employment or income evidence before
disbursing your personal loan.
● The lender may reassess information when circumstances change. RBI
requires regulated entities to capture economic information such as
occupation and income when assessing borrower creditworthiness.

Your personal loan eligibility can change when your new employment changes your income details. However, a higher or lower salary does not automatically produce a particular lending decision.
Consider these situations:
● Higher income: Your increased verified income can strengthen repayment capacity.
● Lower income: Lower income can reduce the amount you can comfortably allocate towards repayment.
● No salary credit yet: A recently joined employee may have limited current
salary evidence.
● Different compensation structure: A new salary may include components
that require additional documentation or verification.
CIBIL states that lenders use credit information and specialised personal-loan risk assessment to evaluate applicants. Therefore, personal loan after job change decisions depend on the lender's assessment of your updated financial profile, not the job switch alone.
This distinction matters because personal loan disbursal delay can arise from unresolved verification rather than from an automatic rejection.
Your personal loan documents required can vary by lender and applicant profile. Still, after applying for a personal loan, keep current income and employment records available.
● Recent salary slips: They establish recent earnings. The bank asks salaried applicants for salary slips as part of its stated documentation.
● Bank statements: They can show recent salary credits. The bank requires a salary-account statement as part of its listed documentation.
● Current employment proof: Your lender may request evidence of your new employment where necessary.
● Updated income information: Provide revised details when your compensation changes.
In other words, personal loan documents required after a job change depend on what information your lender needs to verify.
Take these steps before the employment transition creates an avoidable personal loan disbursal delay:
1. Tell the lender about the job change during personal loan application while your application remains active.
2. Keep your latest salary slips and bank statements ready.
3. Keep new-employment records available if the lender requests them.
4. Ask whether the lender needs updated information before disbursing the personal loan.
5. Respond promptly to requests linked to your personal loan application.
A job change during personal loan application should not leave you second-guessing your financial decision. Before your plans move ahead, check your lender’s communication channels, understand your application status and keep your contact details current. A little clarity can prevent unnecessary stress when timing matters.
Track your loan application and take the next step with confidence.